Overview of the Physical, Engineering, And Life Sciences Market
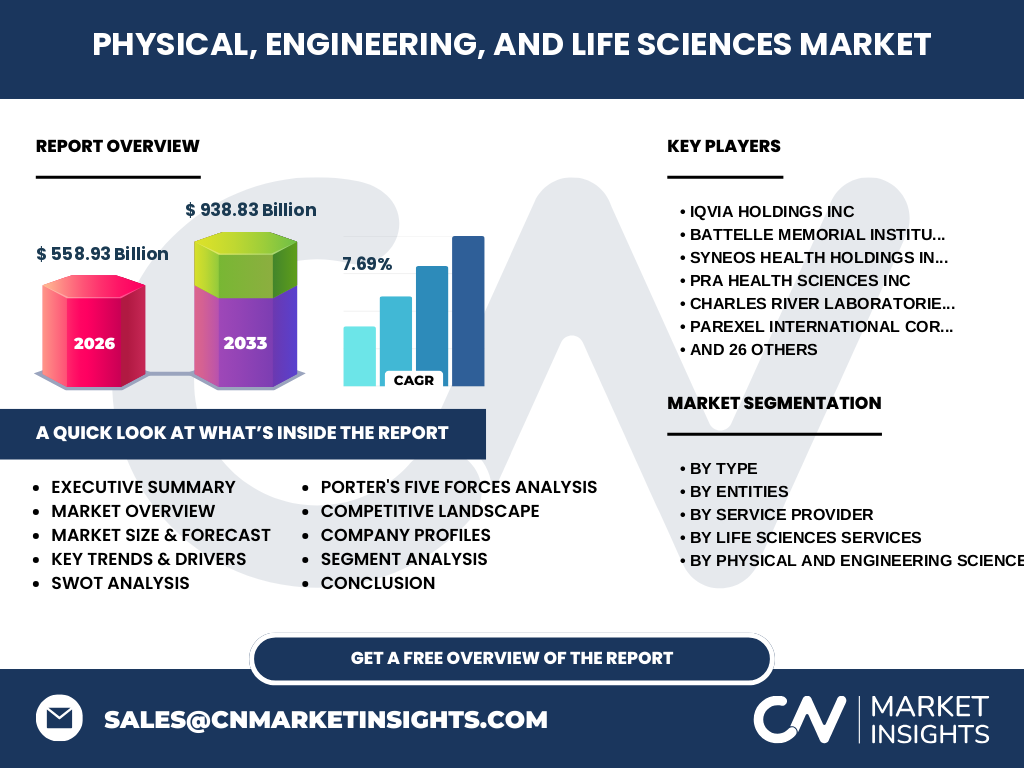
The Physical, Engineering, And Life Sciences Market serves as the bedrock of global R&D, encompassing critical technical services that bridge laboratory breakthroughs with industrial applications. With a 2026 valuation of 558.93 Billion, this sector is essential for maintaining global competitiveness in aerospace, clinical research, and advanced materials science. It integrates high-precision engineering workflows with complex life science regulatory pathways to drive modern innovation.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by a 7.69% CAGR, underpinned by the urgent need for biotechnology scaling and automated manufacturing. While demand for precision instrumentation from firms like Danaher Corporation remains robust, the market faces significant hurdles, including stringent regulatory compliance enforced by bodies like the FDA and EMA. Logistical strain on the supply of rare high-purity raw materials remains a persistent bottleneck.
Emerging Trends and Technological Shifts
The shift toward digital-first laboratory environments is transforming the sector. We observe a rapid adoption of Bioinformatics Services and Robotics and Automation within the Physical and Engineering segment. Companies such as Illumina Inc. and Intuitive Surgical Inc. are leading this pivot, enabling higher throughput and greater diagnostic accuracy, which is essential to reaching the projected 938.83 Billion valuation by 2033.
COVID-19 Impact and Recovery Trajectory
The pandemic acted as a cataclysmic accelerator for the life sciences segment, particularly within Clinical Trials Management and Molecular Diagnostics Services. While physical engineering projects faced initial delays due to supply chain disruptions at major ports, the subsequent recovery trajectory was rapid. The surge in demand for QIAGEN N.V. diagnostic testing kits underscored the critical nature of these services during global health crises.
Competitive Benchmarking and Market Concentration
The competitive landscape is characterized by high market concentration among specialized CROs and technology providers. Industry giants like IQVIA Holdings Inc and Thermo Fisher Scientific Inc. leverage deep-integrated service models to maintain dominance. Meanwhile, firms like Battelle Memorial Institute occupy a distinct niche, providing the high-level expertise needed for complex government-backed engineering initiatives alongside traditional life sciences entities.
Executive Summary: Synthesis of Key Market Findings
Our analysis confirms that the market is transitioning into a high-growth phase, forecasted to reach 938.83 Billion by 2033. The synergy between engineering precision and biological R&D is creating new value pools. Stakeholders should prioritize investments in automated discovery platforms and regulatory-compliant infrastructure, as these areas demonstrate the highest resilience against economic volatility and shifting trade policies.
Market Forecasts: 2027-2033 Projections
Based on current trajectories, we anticipate consistent expansion at a CAGR of 7.69%, culminating in a market size of 938.83 Billion by 2033. This growth is supported by an increased reliance on specialized outsourced engineering and Drug Discovery Services. Emerging economies are expected to capture a larger share of service delivery, driven by the localization of complex manufacturing and clinical trial operations.
Segmentation Analysis: Breaking Down the Industry
The market is bifurcated into two primary pillars: Physical and Engineering Sciences and Life Sciences Services. The former focuses on sectors ranging from Aerospace Engineering to Nuclear Engineering, while the latter encompasses Clinical Research Services and Biotech/Pharmaceutical Services. These segments serve both large enterprise accounts and smaller, agile firms, ensuring coverage across diverse industrial and medical verticals.
Regional Market Performance Dynamics
Geographic performance remains polarized by regulatory maturity and infrastructure density. North America maintains the highest market share due to established research hubs, while the Asia-Pacific region shows the fastest growth in Bioinformatics Services. European markets, characterized by stringent environmental and safety regulations, continue to lead in Chemical Engineering and Environmental Engineering, ensuring that regional growth remains aligned with sustainable development goals.
In-depth Regional Review
North American growth is driven by heavy investment from DARPA and major private firms like Agilent Technologies Inc., while European performance remains anchored by companies like Merck KGaA. We observe significant logistical hurdles in emerging markets due to the need for cold-chain infrastructure in life sciences, whereas physical engineering markets there are benefiting from massive infrastructure investments in urban robotics and renewable energy systems.
Strategic Positioning of Leading Players
Leading companies have adopted distinct strategic postures. Charles River Laboratories International Inc. focuses on broad-based contract research, while Hitachi High Technologies America Inc. emphasizes high-end instrumentation. WuXi AppTec Co. Ltd. has successfully positioned itself as a critical node in the global outsourcing chain, bridging East-West research gaps to gain significant market traction.
Porter’s Five Forces Assessment
The threat of new entrants is moderate, mitigated by high capital expenditure requirements for specialized lab infrastructure. Supplier power is high for unique reagents and high-grade materials, while buyer power is concentrated among large pharmaceutical firms. Intense rivalry among top-tier CROs ensures that competitive differentiation is driven by technological capability rather than price alone.
SWOT Analysis: Strategic Outlook
Strengths: Deep integration with global R&D. Weaknesses: High dependence on specialized, non-substitutable talent. Opportunities: Increased focus on AI-driven Drug Discovery Services and Robotics and Automation. Threats: Escalating geopolitical tensions impacting supply chains and varying international regulatory landscapes that could impede cross-border collaboration and service deployment.
Value Chain Analysis
Value flows from foundational material suppliers to high-value service providers. Raw material procurement—essential for Materials Science—is followed by laboratory or engineering design. Contract Research Organizations (CROs) then act as vital intermediaries, facilitating the translation of research into commercial products for end-users, ultimately ensuring that innovation reaches the market through efficient regulatory and validation channels.
Investment Insights and High-Potential Areas
We identify Bioinformatics, Molecular Diagnostics, and Autonomous Robotics as the highest-potential areas for capital allocation. Investors should target companies capable of navigating complex regulatory affairs while scaling production through large enterprise solutions. The shift toward decentralized clinical trials also presents an overlooked opportunity for firms specializing in digital patient data management.
Conclusion and Key Takeaways
The sector's resilience, demonstrated by the growth toward 938.83 Billion by 2033, confirms its status as a vital component of the global economy. Companies must prioritize technological agility and compliance resilience to thrive. The integration of Life Sciences with advanced engineering solutions will be the definitive marker of success for market leaders over the coming decade.
Research Methodology: How Data is Triangulated
Our baseline estimates are triangulated using a rigorous three-pillar approach: direct trade registry data, comprehensive primary stakeholder interviews with industry executives, and secondary macroeconomic indicators. This method accounts for both top-down market performance and bottom-up entity growth, ensuring our CAGR of 7.69% is grounded in verifiable, actionable intelligence.
Scope of the Report and Coverage Parameters
This report covers the global Physical, Engineering, And Life Sciences Market, focusing on services provided by Organizations, Partnerships, and Sole Traders. Our scope explicitly excludes consumer-grade electronics but includes deep-tech engineering and specialized clinical laboratory services. Geographical analysis spans the Americas, EMEA, and APAC, providing a comprehensive assessment of the competitive dynamics shaping this industry.
Recent Market Developments and Strategic Moves
Recent activity is dominated by M&A and strategic partnerships designed to enhance vertical integration. Significant announcements from companies like Bruker Corporation and PerkinElmer Inc. reflect a trend of consolidating advanced instrumentation under single service umbrellas. These moves facilitate a more seamless R&D lifecycle, allowing small and medium enterprises to benefit from the advanced platforms once exclusive to large enterprise players.